Zach Abraham, Author at Bulwark Capital Management
All Posts By

Zach Abraham

What Is Financial Planning? A Guide To Your Complete Financial Picture

By | Financial Planning

Fall is a great time to take a step back and look at all of your financial matters as a whole. A comprehensive financial plan considers more than retirement savings. It also accounts for retirement income, major life goals such as buying a home or saving for college, insurance to help protect against unexpected events, budgeting, investments, and legacy planning.

Looking at how these pieces work together can help you identify gaps, prioritize your goals, and make more informed financial decisions.

The Bigger Picture

A financial plan is more than a collection of accounts. It’s a strategy for the life you want to live. Your goals, savings, investments, taxes, and protection strategies all play a role in your financial future.

Many people approach their finances one decision at a time, but these areas aren’t independent. Whether it’s contributing to a retirement account, paying off debt, or saving for a home, these decisions can affect one another. Think about how your cash flow influences how much you can save and invest, or how your tax situation affects how you structure retirement income.

Comprehensive financial planning takes a broader approach. Instead of looking at each financial decision independently, it considers how different parts of your financial life affect one another.

Your Goals Come First

Before deciding where your money should go, take a step back and think about what you want that money to accomplish. Your financial decisions should be connected to intention, rather than blindly investing or saving without a clear purpose or direction.

Where do you want your financial journey to lead? What are you working toward?

  • Short-term goals: Build emergency savings, pay off debt, or plan a vacation.
  • Mid-term goals: Buy a home, start a business, or fund education.
  • Long-term goals: Retire comfortably, build wealth, or leave a legacy.

What Should A Financial Plan Include?

A comprehensive plan is really a full, 360 view of your financial life, typically including:

  • Your goals
  • Investment strategy
  • Retirement plan
  • Cash flow management
  • Emergency savings
  • Debt management
  • Insurance needs
  • Tax strategy
  • Estate and legacy plan

Build With Growth & Protection In Mind

Building wealth is important but protecting what you’ve built is just as important. Unexpected expenses, illnesses, a loss of income, or other major life events can affect your finances and put obstacles between you and your goals, making it harder to stay on track.

That’s why it’s important to look at both growing your wealth and protecting what you have. Emergency savings can help cover unexpected costs, while insurance coverage can help reduce the financial burden of illness, disability, property damage, or the loss of a loved one. Estate planning can also help ensure your assets are managed and passed on according to your wishes.

While you can’t plan for everything, you can take steps to prepare for potential challenges and mitigate risks.

Review And Adjust

Your financial plan should reflect your life as it is today, not just the goals you set when you first created it. Because life and financial priorities change, your plan should be reviewed and adjusted over time, particularly after major life events, such as getting married, having a child, changing jobs, buying a home, or approaching retirement. As your income, expenses, family, and priorities change, your financial needs may change, too.

Reviewing your plan at least once a year can help you track your progress, revisit your goals, and identify areas that may need attention. You may not need to make major changes every time you review your plan. Sometimes, it’s simply a matter of confirming that you’re on track. Other times, you may need to adjust your savings, investments, insurance coverage, or retirement strategy to reflect your current circumstances.

Turn Your Plan Into Action … With Help!

Understanding your finances is the starting point. A comprehensive financial plan helps turn your goals into actionable steps, giving you a way to track progress and adjust as your needs change. It covers key areas such as budgeting, savings, debt, investments, retirement, taxes, insurance, and estate planning and should reflect where you are today, where you want to go, and the steps that can help you get there.

While it’s possible to build a comprehensive financial plan on your own, professional guidance may be helpful if you’re unsure where to start or how to approach more complex financial decisions. A financial advisor can help you evaluate your options, develop strategies around your goals, and determine when you may benefit from working with specialists in areas such as estate planning, taxes, or insurance.


Before you can put your financial plan into action, you need a plan built around your goals. Ready to take the first step? Contact us today to learn more! Bulwark Capital Management can help you stay on track, adjust as needed, and support you in making steady progress toward your financial future.


This content is for informational and educational purposes only and should not be construed as tax, legal, or individualized financial advice. Always consult with your tax advisor, attorney, and/or qualified financial professional regarding your specific situation before making any retirement plan or tax-related decisions.

Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-186


Sources:

https://www.investopedia.com/terms/f/financial_plan.asp

https://www.wsj.com/buyside/personal-finance/financial-advisors/comprehensive-financial-planning

https://www.nerdwallet.com/financial-advisors/learn/what-is-a-financial-plan
Fall Favorites: Making The Most Of The Season Before Or In Retirement

By | Lifestyle

There’s something about fall that feels different. Maybe it’s the cool weather, the return of football season, or the pleasure of spending a Saturday afternoon at a pumpkin patch with family. For many people, fall serves as a reminder that life moves through seasons. The good news? This can be one of the most enjoyable stages of life.

A Trip to the Pumpkin Patch

Pumpkin patches aren’t just for young families anymore. Many have expanded into full-day experiences with hayrides, farmers markets, local food vendors, craft fairs, and live entertainment. They’re a great opportunity to spend time with children, grandchildren, friends, or simply enjoy a relaxing day outdoors. As retirement approaches or when you’re in retirement, many people begin looking for experiences rather than possessions. A day spent making memories often provides more satisfaction than another purchase that ends up collecting dust.

Football Saturdays and Sundays

Fall and football go hand-in-hand. Whether you’re cheering for your favorite college team on Saturday or watching NFL games on Sunday, football season has a way of bringing people together. Tailgates, watch parties, and family gatherings create opportunities to connect with the people who matter most. Many discover that one of the things they look forward to most isn’t necessarily having more money. It’s having more time to enjoy the activities they love.

Thinking About or Living Your “Retirement Lifestyle”

When people think about retirement planning, they often focus on numbers: 401(k) balances, investment returns, Social Security benefits, and Retirement dates.

Those items are important, but it’s equally important to ask:

What do I want my retirement to look like?

  • Will you spend more weekends traveling?
  • Attend more football games?
  • Take annual family trips?
  • Volunteer?
  • Golf more often?

The answer helps determine how much income you’ll need and what kind of retirement strategy can support the life you want to live.

Enjoy the Season

Fall is a reminder that life isn’t just about preparing for the future. It’s also about enjoying the present. So, visit the pumpkin patch. Go to the football game. Spend time with family and friends. Create memories while you can. And as you do, think about how you want future fall seasons to look when work becomes optional and retirement becomes reality. After all, whether in retirement or in retirement, planning isn’t just about building wealth.

It’s about creating the freedom to enjoy life’s next season. Bulwark Capital Management can help you stay on track, adjust as needed, and support you in making steady progress toward your financial future.


Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-186

How Grandparents Can Build A Lasting Financial Legacy

By | Financial Planning, Legacy Planning

Grandparents Day, celebrated on September 13, is a chance to recognize the important role grandparents play in their families, from offering guidance and support to helping raise the next generation. For many retirees, that support extends beyond spending time with children and grandchildren. It can also include helping with college education costs and making thoughtful decisions about the assets and wealth they hope to pass down.

How assets are managed, gifted, and passed down can have important implications for taxes, financial aid, and the financial well-being of future generations. Here are some considerations grandparents may want to keep in mind.

What Happens to Retirement Accounts When You Leave Them to Heirs?

As a grandparent, you may have decided to add a child or grandchild as a beneficiary on your taxable 401(k) or IRA or similar retirement account without understanding the additional tax implications that occurred due to the SECURE Act which became law in 2020.

The Setting Every Community Up for Retirement Enhancement (SECURE) Act changed the tax treatment of inherited retirement accounts by non-spouse beneficiaries, eliminating the more favorable so-called “stretch IRA” used prior to its enactment.

Now, due to a new 10-year rule, a retirement account inherited by a non-spouse generally must be fully distributed by December 31 of the 10th year after the year of the original owner’s death and the inherited account closed. (Certain eligible beneficiaries, including surviving spouses, the account owner’s minor children, disabled or chronically ill individuals, and beneficiaries who are not more than 10 years younger than the account owner, may be subject to different rules.)

Not only that, but depending on the circumstances, heirs may also be required to take annual distributions, called RMDs or required minimum distributions, during that 10-year period. For example:

  • If the account owner dies before age 73, when they were required to start taking RMDs: The heir may have more flexibility about when to take distributions during the 10-year period.
  • If the account owner dies after they were already required to take RMDs: The heir may have to take certain annual distributions during the 10-year period, in addition to ultimately emptying the account by the end of year 10.

RMDs and distributions from traditional IRAs and 401(k)s are taxed as ordinary income rather than at capital gains rates, and in most cases, these required withdrawals will increase an heir’s taxable income and result in a larger tax bill, leaving them with less of an inheritance from you. (NOTE: Inherited Roth IRAs and Roth 401(k)s are also generally subject to the 10-year distribution rule for many non-spouse beneficiaries, but qualified distributions are generally tax-free.)

As you can see, it’s not just about how much you leave your heirs. It’s about how much of that inheritance they can ultimately keep after taxes. For grandparents creating a financial legacy, understanding these rules can be an important part of deciding how different assets may support the next generation. Consider taking action now on your retirement accounts.

Does A Grandparent-Owned 529 Plan Affect FAFSA?

Many grandparents have the goal of helping their grandchildren with college costs. A type of account called a 529 plan, sponsored by a state or state agency, is designed for saving for education expenses. Following the enactment of the FAFSA Simplification Act in December of 2023, rules surrounding 529 college savings plans became more favorable for grandparents wanting to help their grandchildren with college expenses.

FAFSA, or the Free Application for Federal Student Aid, is the online form students in the United States fill out to get financial help for college in the form of grants or loans. Unlike previous FAFSA rules, now grandparent-owned 529 plans are no longer reported as student assets or student income on the FAFSA. That means grandparents who want to open and contribute to their own 529 plans can now do so knowing that the savings they accumulate and spend on behalf of their grandchild won’t affect financial aid eligibility.

529 plans also offer tax-free investment growth and tax-free withdrawals when the money is used for qualified education expenses. This allows grandparents to build a college fund for a grandchild while providing potential tax benefits along the way.

However, keep in mind that while 529 plans are no longer considered on the FAFSA, some colleges and universities also use the CSS Profile to determine eligibility for institutional financial aid. These accounts may be treated differently under the CSS Profile.

You should also be aware that if 529 plan funds are not used for qualified education expenses, taxes and penalties may apply. Additionally, if the named beneficiary does not use the funds for education, you can change the beneficiary only to eligible family members, including siblings, parents, first cousins, children, certain in-laws or yourself, for qualified education expenses. Depending on the educational goals of your family members, you may want to choose a more flexible type of investment.

How Can Grandparents Plan For Multiple Generations?

Grandparents often think about what they can leave behind for their children and grandchildren. But creating a meaningful legacy involves more than simply giving money away. Consider creating a multigenerational financial and estate plan which can help you:

  • Contribute toward a child or grandchild’s education while considering how those assets may affect financial aid.
  • Determine which assets to pass on, who should receive them and when they should receive them.
  • Consider how gifts, inherited assets, retirement accounts and other investments may be taxed when wealth moves between generations.
  • Establish structures that can help preserve assets and provide greater control over how inherited wealth is used.
  • Use gifting and other strategies to help children and grandchildren build financial security.

A Legacy Is More Than What You Leave Behind

The founder of Grandparents Day was Marian McQuade, a West Virginia homemaker who wanted to encourage young people to “tap into the wisdom and heritage their grandparents could provide.”

That wisdom and heritage are part of what makes a family legacy meaningful. Passing down wealth can be another way to carry that legacy forward, and it means more than simply giving money away. Grandparents are living bridges between generations, carrying forward a family’s true wealth: the wisdom, values, priorities, and traditions that help shape its future, along with the financial resources that can support generations to come.


Your legacy can shape generations to come. Contact us today to explore strategies for managing, protecting, and transferring multigenerational wealth while carrying your values forward. Bulwark Capital Management can help you stay on track, adjust as needed, and support you in making steady progress toward your financial future.


This content is for informational and educational purposes only and should not be construed as tax, legal, or individualized financial advice. Always consult with your tax advisor, attorney, and/or qualified financial professional regarding your specific situation before making any retirement plan or tax-related decisions.


Sources:

https://en.wikipedia.org/wiki/SECURE_Act

https://www.hallmark.ca/en/get-inspired/history-of-grandparents-day/

https://www.savingforcollege.com/article/new-fafsa-removes-roadblocks-for-grandparent-529-plans

https://investormint.com/uncategorized/inherited-ira-rules-after-secure-act-2026-guide

https://www.irs.gov/publications/p590b

https://www.savingforcollege.com/article/who-maintains-control-529-plan


Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-163

Sick,Woman,Blowing,Her,Nose,With,A,Tissue,On,A

Support Your Immune System Before Cold Season

By | Lifestyle
Fight the Cold Before it Gets Cold

Everyone knows the feeling: You wake up one morning with a dry, scratchy throat, maybe a little congestion, a runny nose, or a possible headache, but it’s the unmistakable sense that you might be coming down with something.

Unfortunately, there is no guaranteed way to stop a common cold once it begins. Most colds are caused by viruses and resolve on their own, typically within a week or two. However, taking a few preventative measures may help support your immune system. With cold and flu season right around the corner, try implementing these lifestyle steps to help potentially reduce your chances of getting sick.

Prioritize Your Sleep

You may have heard it before: “Make sure you get enough sleep,” but it seriously does make a difference. Research has linked inadequate sleep with impaired immune function, making getting enough sleep especially important when you start feeling under the weather. It’s OK to slow down. That may mean going to bed earlier, taking a nap, or cutting back on your normal schedule.

Your sleep environment can matter, too. If temperatures drop where you live, make sure you are properly bundled up and comfortable at night, so the cold doesn’t interfere with your sleep.

Stay Hydrated and Reach for Warm Liquids

Drinking plenty of fluids is another recommendation that appears consistently among many professionals. Staying hydrated is important year-round, but it can be especially easy to overlook during colder months. Cold, dry air can leave you feeling dehydrated and may contribute to an irritated throat, so drinking enough fluids throughout the day can help prevent dehydration and keep you comfortable. Warm liquids such as tea, broth, or warm water with lemon may also help loosen congestion and soothe an irritated throat if you start noticing minor symptoms.

Consider Supplements Early

Zinc and vitamin C are two nutrients commonly associated with supporting the immune system, but the research is more complicated than simply saying they can prevent a cold.

Zinc has compelling evidence for potentially shortening an existing cold, particularly when taken soon after symptoms appear. Vitamin C has not been shown to reliably prevent or cure a cold once it begins, although regular vitamin C intake may reduce the duration of colds for some people. Getting vitamin C through foods is generally preferred over relying on large doses of supplements.

If you are considering supplements, talk with your health care provider about the appropriate product and dosage. They may have side effects and excessive intake can be harmful, especially if you take medications or have an underlying health condition.

Still Get Your Exercise

We know that when the weather starts to get cold, it gets a lot harder to keep up with regular activity, but this is still an important part of supporting your overall health and immune system. The CDC notes that physical activity can help you feel better, sleep better and reduce anxiety, while emerging research suggests that physical activity may also benefit immune function.

You don’t have to spend hours at the gym to benefit. Walking, climbing stairs, biking, or other moderate activities can help. For most adults, the goal is at least 150 minutes of moderate-intensity physical activity each week or 75 minutes of vigorous activity.

Balance Your Nutrients

Your immune system relies on a variety of nutrients to function properly, making a balanced diet an important part of staying healthy all year round. Focus on plenty of vegetables and fruits, lean proteins, dairy products or alternatives, healthy fats and whole grains. Limit highly processed foods, saturated fats, excess sodium, and added sugars.

As we mentioned earlier, a healthy diet can provide many of the nutrients you need, including vitamins and minerals such as vitamin C and zinc. Think of your diet as the fuel your body uses every day. The better you nourish it, the better equipped your body is to support your overall health.

As we head into cold and flu season, start with the basics: rest, sleep, hydration, exercise and food. These strategies aren’t guaranteed to stop you from getting a cold, but rather are part of living a healthier lifestyle to help maintain your immune system.


Bulwark Capital Management can help you stay on track, adjust as needed, and support you in making steady progress toward your financial future.


Sources:

https://www.ynhhs.org/articles/4-ways-kill-cold-starts

https://www.webmd.com/cold-and-flu/cold-and-flu-treatment-checklist

https://pmc.ncbi.nlm.nih.gov/articles/PMC5949172/

https://www.psychologytoday.com/us/blog/evidence-based-living/201711/how-to-beat-the-common-cold

https://rightasrain.uwmedicine.org/well/cold-remedies

https://www.cdc.gov/healthy-weight-growth/about/enhancing-immunity.html

https://www.mdanderson.org/cancerwise/6-simple-ways-to-boost-your-immune-system.h00-159781968.html


Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-163

This Back-to-School Season, Teach Your Kids and Grandkids About Money

By | Financial Literacy

It’s back-to-school time again, when our children and grandchildren return to the classroom for a new school year of learning. While reading, writing, and arithmetic usually take center stage, other subjects are also important, such as personal finance. In fact, since around 2021, recognition of the importance of educating students about money and finance has burgeoned, and classroom requirements have been implemented by the majority of states in America according to the Council for Economic Education.

Personal finance coursework is now required by 39 states in order for a student to graduate from high school.

This is a much-needed development, but we think you should start younger than high school age. Even kindergarteners can begin to understand money concepts. While they might not be ready for an explanation about stock market risk, or what a 529 plan is, they can learn the basics about how money works if you teach them.

A great way to introduce children to how money works is to give them an allowance for age-appropriate household chores.

Once your child starts earning money, you can coach them on how to divide their money into “spend, save, and share” categories. You can use separate piggy banks for each category, label special envelopes, or use clear jars so they can see money building up. Any method that’s visual and understandable will work.

Here’s how it might break out.

THE SPEND JAR:

This portion is for immediate enjoyment or day-to-day expenses. Kids can use this money to buy things they want, like toys, games, or treats. They will quickly understand this category if they don’t already, and most children will want to spend all of it. This is where money concepts become teachable opportunities for you as a parent or grandparent.

THE SAVE JAR:

The save category is for money your child can put away for larger future goals that will take time to save for. If your child wants a toy that is more expensive, explain that they can save part of their money for that larger purchase. For instance, if the item they want is $20 and they save $5 per week, they can save and buy that toy in one month. You could even mark a calendar to count down the days. As they get older and more capable of delayed gratification, perhaps they will want to save for a musical instrument, or a car when they turn 16.

THE SHARE JAR:

This category is for money set aside for giving to others, whether through charity, tithing, helping someone in need, or just the sheer joy of gifting. Some parents or grandparents may want to teach that 10 cents of every dollar should go into this category for religious reasons. Or sometimes children might want to buy gifts for their loved ones on birthdays or holidays, or pay for an ice cream outing for themselves and a friend as a way to share abundance and fun. The share category opens a whole new dimension to money and what it can be used for.

But there’s more to learning about money than just the spend, save, and share jars. Other things you may want to consider include allowing your child to hand a cashier their money to purchase their chosen items to help them build confidence. Comparing price options between brands to help teach them about budgeting. Or making a rule that kids have to wait a certain time period before making toy purchases in case they change their minds. Other teachable moments might happen spontaneously, like if an item they purchased with their money breaks and what recourse they might have or don’t have with that purchase. You can also have a conversation about quality over quantity, and what really matters in life.

Another idea to consider for children as they get older is creating a “contract” for chores that is renewable yearly. That way, you can also teach them about taking on more responsibility, negotiating fair wages for work, and knowing their worth and value as they get older and can do more.

It’s also important to remember that your children learn so much by simply observing you. If you are demonstrating good financial principles in front of them already, they’ll naturally pick up on what you do and how it matches with what you say. This is why it’s important to make sure you keep up with your own financial health.

Through the years, you can start including children in more complex financial conversations. You can teach them about how to build good credit, what different types of investments are, risk versus reward, and what your plans are when it comes to your wealth transfer legacy.


We are here to help our clients grow and protect wealth, and pass on a tax-advantaged legacy you can be proud of. Contact us at any time to discuss your situation. We welcome the chance to speak with you. Bulwark Capital Management can help you stay on track, adjust as needed, and support you in making steady progress toward your financial future.


Sources:

https://www.councilforeconed.org/four-new-states-implement-personal-finance-courses-as-cees-survey-of-the-states-reveals-positive-momentum-in-financial-literacy-education-in-america/


DISCLOSURE

Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-142

Just Book, Pack, and Go: Vacations That Require Minimal Planning

By | Lifestyle

As summer winds down and the back-to-school season begins, don’t think you’ve missed your chance to squeeze in one last getaway. Just book, pack, and go with these vacation ideas that require minimal planning!

All-Inclusive Resorts

All-inclusive resorts are hard to beat when you’re looking for a vacation that requires very little planning! Instead of spending hours researching restaurants, activities, transportation, and daily expenses, all you have to do is choose the destination that you’re most interested in, compare a few resorts, and book the one that best fits your travel style and budget!

All-inclusive resorts offer a variety of package options and even offer different pricing tiers, allowing you to customize your stay based on what matters most to you. For example, some packages include unlimited premium beverages and top-shelf spirits, while others focus on meals and activities for the whole family. This makes it easy to find an option that fits both your preferences and your budget. Depending on the resort you choose, your stay may include unlimited meals/food, room service, nightly entertainment, fitness classes, children’s clubs, kayaking and paddleboarding, snorkeling, horseback riding, spa treatments, cultural experiences, and guided excursions.

Every resort is different, so it’s worth taking your time initially to compare what’s included before you book. You’ll spend less time planning and budgeting throughout your trip, and once you’ve booked your stay, you can truly sit back and relax. Use websites like Expedia to compare destinations, resorts, and package options, or if you’re a Costco member, don’t forget to browse Costco Travel! They offer exceptional vacation packages that include exclusive member pricing, resort credits, transportation, or other perks.

Cruises

Now, if you love the convenience of an all-inclusive resort but also want to experience multiple destinations, a cruise may be your idea of the perfect last-minute vacation. Think of it as an all-inclusive resort that travels with you. Your accommodation, dining, entertainment, and many onboard activities are bundled into one experience, allowing you to once again spend less time planning and more time enjoying your trip.

The main difference between choosing an all-inclusive resort or a cruise is the opportunity to visit several destinations in a single vacation. Your ship will stop at multiple ports, giving you the chance to explore different cities, beaches, and cultures along the way. You’ll have plenty of options without having to coordinate transportation or change hotels.

Cruises also come in a wide variety of lengths and styles. If you’re looking for a spontaneous getaway, many cruise lines offer weekend or three- to four-day itineraries. If you have more time, you can choose week-long or even extended voyages. There’s also a cruise for nearly every type of traveler. Families may enjoy a Disney cruise, while couples or groups of friends might opt for an adults-only cruise, and there are even themed cruises, such as murder mystery experiences. If you’re looking for a slower-paced, scenic experience, river cruises offer a unique way to explore charming towns and historic cities. Some cruise lines are known for luxury accommodations, fine dining, and premium service, while others pride themselves on family-friendly activities, exciting entertainment, and nonstop amenities. It all comes down to your travel preferences.

In fact, with everything there is to do onboard, you may even forget you’re on a boat!

Staycations

Not every vacation requires boarding a plane or traveling hundreds of miles from home. While a staycation may require a little more planning than an all-inclusive resort or cruise, it’s still one of the easiest ways to enjoy a relaxing escape without extensive travel.

The idea behind a staycation is simple: choose a destination that’s close enough to drive to, but far enough away that it feels like a true vacation. Since you’re likely already familiar with the area, planning becomes much easier. You may already know of a luxury hotel you’ve always wanted to try, a spa you’ve heard great things about, or local attractions and restaurants you’ve been meaning to visit. When choosing a staycation, you can skip the airport, avoid long travel days, and treat yourself to a change of scenery to recharge.

Every region has something unique to offer. In Arizona, many residents escape the summer heat by heading north to Flagstaff or Prescott, where cooler temperatures, mountain cabins, and hiking trails provide a completely different experience. Californians who need a break from the coast can venture inland to explore the breathtaking scenery of Yosemite National Park, while those living in the busy city of Chicago can enjoy a relaxing getaway along the shores of Lake Michigan. Michigan residents can also take a trip to Mackinac Island, which has consistently been recognized as one of America’s top summer destinations.


Vacations are meant for relaxation and new experiences that take you away from your daily routine and planning them shouldn’t add to your stress. We hope you’re able to disconnect, recharge, and enjoy every moment of your next getaway.

If you’d like help incorporating travel into your financial plan so you can still feel confident about reaching your retirement goals, contact us today to start the conversation!


Sources:

https://www.costcotravel.com/vacation-packages/mexico

https://www.ace.aaa.com/travel/advocacy/last-minute-summer-trips.html

https://creators.yahoo.com/lifestyle/story/5-last-minute-family-summer-vacation-ideas-that-are-actually-affordable-131817758.html

https://www.cruisecritic.com/articles/best-short-cruises

https://michiganindependent.com/features/mackinac-island-named-best-summer-travel-destination-in-national-poll/

DISCLOSURE

Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-142


How Can I Maximize My Mid-Year Tax Deductions?

By | Tax Planning

Many new large and complex tax laws have been passed in the last decade, with clauses slowly taking effect through time and being clarified by the IRS to this day. These include the original Tax Cuts and Jobs Act (TCJA) of 2017, the Setting Every Community Up for Retirement Enhancement (SECURE) Act of 2019, the SECURE Act 2.0 of 2022, the Inflation Reduction Act (IRA) of 2022, and the One Big Beautiful Bill Act (OBBBA) of 2025.

With these new complexities on top of the already-existing complicated tax laws, instead of waiting until the end of the year, we want to encourage everyone to get pertinent tax advice from their team of financial, legal, and tax professionals now, mid-year, while they still have plenty of time to take action.

Personalized tax advice from tax professionals is always recommended. But we wanted to give you a few things to consider, for informational purposes only.

Can I benefit from charitable contributions?

  • For non-itemizers, you can still claim an “above the line” deduction on your 2026 tax return for cash gifts to qualifying charities, excluding donor-advised funds and private foundations. Single people can claim up to $1,000; married up to $2,000. NOTE: Non-cash or in-kind donations of property are not deductible for those using the standard deduction.
  • For those who itemize, you can still use Schedule A, but you can only deduct contributions that exceed .5% of your adjusted gross income. For example, if your AGI is $100,000, only donation amounts in excess of the first $500 are tax-deductible. Non-cash, in-kind donations are deductible over the threshold, but must meet new, stricter rules to substantiate fair market value of the items. For donated items valued over $500, you must file IRS Form 8283, and an independent appraisal is generally required for property valued over $5,000. For those in the top income tax bracket (37%), the tax benefit of charitable deductions is reduced from 37 cents to 35 cents per dollar donated.
  • If you have a tax-deferred IRA (individual retirement account) and you are at least 70-1/2 years old, you might be able to make a direct QCD, or Qualified Charitable Contribution to an eligible nonprofit, allowing you to exclude up to $111,000 from your gross income. You can also use QCDs to satisfy your annual required minimum distributions, eliminating part or all of your tax bill on otherwise taxable RMDs.

Can I “bunch” my tax deductions?

With the standard deduction amount at $16,100 for single filers and $32,200 for those filing jointly in 2026, itemizing your tax returns only makes sense if your deductions exceed these amounts. Bunching multiple years’ worth of charitable donations, state and local taxes (SALT), large medical expenses, and other claimable deductions into a single tax year may be possible to help you surmount the standard deduction threshold.

Will I be able to make catch-up contributions for the 2026 tax year?

Maximizing contributions to tax-deferred qualified accounts is a strategy used by some to reduce taxable income. For those aged 50 or older, be aware that there are new requirements for catch-up contributions to workplace plans for 2026.

  • $150,000 or less in income

For those who earn less than $150,000, you can still make catch-up contributions to your workplace traditional 401(k) or similar pre-tax accounts, or to your Roth accounts if your employer offers them. It’s your choice. Those aged 50 or older can contribute an additional $8,000 catch-up amount on top of their standard $24,500 contribution limit for 2026, while those aged 60 through 63 are allowed “super catch-up” amounts of $11,250.

  • $150,000 income or more

For those who earn $150,000 or more, catch-up contribution amounts can only be made to after-tax Roth accounts beginning this year. If your workplace doesn’t offer a Roth option, you cannot make catch-up contributions in 2026.

  • IRA catch-up amounts

For those who own their own traditional IRA or Roth IRA accounts, you may be able to contribute $7,500 for 2026 if you meet income and other IRS requirements. If you are 50 or older, an additional $1,100 catch-up amount may be allowed.

Do I have more tax write-off options as a sole-proprietor or business owner?

The short answer is yes. Here are a couple of recent tax laws that may apply to you as a business owner, but there are many more tax opportunities for businesses you may want to explore.

The OBBBA permanently provides immediate 100% bonus depreciation for eligible assets like vehicles or equipment allowing businesses to write off the entire cost of qualifying property upfront. Bonus depreciation can also be used to create or increase a net operating loss which can be carried forward to offset future taxable income.

The OBBBA also made the QBI deduction permanent with expanded access to more businesses. Pass-through businesses (meaning profits pass through your business to your personal tax return) may be eligible to deduct up to 20% of their QBI or qualified business income if they meet eligibility requirements.

Can a series of Roth conversions help my tax situation?

For those heading toward retirement, don’t forget to explore long-term tax strategies like Roth conversions that you might be able to utilize. There are two ways Roth conversions can reduce taxes for some people. First, you might be able to reduce your overall income tax burden in retirement. Second, you might be able to reduce taxes for your heirs, transferring more wealth to the next generation.

  • For You

Most qualified retirement accounts like 401(k)s are funded with pre-tax dollars. Meaning that your employer diverts your selected contribution amount into your 401(k) account, reducing your annual taxable income by the amount you have contributed. Traditional IRAs (individual retirement accounts) are also funded with pre-tax dollars, and some taxpayers can take tax deductions for IRA contributions if they qualify.

Pre-tax contributions can reduce your taxes while you are building up retirement assets. However, as you get close to retirement, you need to remember that ordinary income taxes will be due on all of that money, and you will be required to start annual withdrawals at age 73, paying income taxes on those amounts every year. Plan custodians are not required to inform you about these RMDs (required minimum distributions), or calculate them for you. You must proactively take them. And there’s no grace period either, RMDs are due by December 31 at midnight each year, not April 15 tax day, with exceptions only in your first year of taking RMDs.

And, surprise! Many find that RMDs from large taxable accounts cause their Social Security benefits to be taxed—from 50 to 85% in some cases when their annual “provisional income” exceeds $44,000 for married couples filing jointly; $25,000 for single filers.

Roth conversions allow you to move money from taxable accounts like traditional 401(k)s over to after-tax Roth IRA accounts, depending on your plan’s rules. If these are done after age 59-1/2, no penalties will apply, but you will owe income taxes on amounts converted in the tax years you make conversions. So, keep in mind this tax strategy only makes sense if you will benefit over the long-term.

Be sure to find professionals you trust to do the math for you and follow all strict IRS rules as Roth conversions cannot be undone. And be sure to ask your financial professional if there are ways to pay for the income taxes that will be due.

As a reminder about Roth accounts, RMDs are not required from them, and any withdrawals you do decide to make are not subject to income tax since they are funded with after-tax money. Principal you have put in can be taken out of a Roth at any age without tax consequences, and same with earnings after five years after you reach age 59-1/2. (Hardship rules apply if you really need to access funds.)

  • For Your Heirs

Many people still don’t understand that non-spousal inheritance rules for traditional taxable accounts like 401(k)s changed drastically because of the SECURE Act of 2019, requiring that the entire inherited account balance be fully withdrawn by the end of the 10th year following the original owner’s death. This change can cause heirs to be thrown into the highest income tax brackets, eating away a large chunk of their inheritance due to taxes. Furthermore, annual RMDs have to be taken by inheritors based on their own life expectancies if the original owner had been taking RMDs. (Note: there are exceptions for Eligible Designated Beneficiaries (EDBs).)

According to the Congressional Research Service, this change, which took effect in 2020, will generate $15.7 billion+ of additional federal tax revenue through 2030; the huge bump coming from compressing these distributions into a single decade.

If you have large taxable accounts and had hoped to leave tax-advantaged legacy wealth to your heirs, be sure to look into how Roth conversions might impact your estate plan in terms of passing on multigenerational wealth. Roth IRAs can be left to heirs tax-free after the account has been in place for five years or more. The only new rule is that heirs must withdraw and close a Roth account within 10 years of inheritance.


###


How will I be able to retire?

If you are concerned about how you will be able to afford to retire, how and when you might finally be able to quit your job, and how you can build tax advantages into your retirement plan, don’t hesitate to reach out to us for a complimentary conversation. Remember that having a 401(k) plan or a portfolio of stocks and bonds is not the same as having an actual retirement plan that maps out your monthly income during the 20, 30, or even 40+ years you might live in retirement.


We focus on retirement planning. Contact us today to discuss your retirement plan! Bulwark Capital Management can help you stay on track, adjust as needed, and support you in making steady progress toward your financial future.


Sources:

  1. https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-catch-up-contributions
  2. https://www.schwab.com/learn/story/social-security-is-taxable-how-to-minimize-taxes
  3. https://www.marketwatch.com/story/secure-act-includes-one-critical-tax-change-that-will-send-estate-planners-reeling-2019-12-30
  4. https://carlmontacademicfoundation.org/news/2025/12/strategies-to-consider-before-the-2026-tax-law-changes/
  5. https://www.fidelity.com/learning-center/personal-finance/tax-brackets
  6. https://www.irs.gov/taxtopics/tc506
  7. https://www.landmarkcpas.com/qbi-deduction-2026-changes-what-business-owners-need-to-know/


This content is for informational and educational purposes only and should not be construed as tax, legal, or individualized financial advice. Always consult with your tax advisor, attorney, and/or qualified financial professional regarding your specific situation before making any retirement plan or tax-related decisions. Retirement plan provisions can vary based on plan design, employer implementation, and individual circumstances. Roth availability and catch-up contribution rules are subject to plan amendments and IRS guidance.


Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-121

Unique Wedding Trends Guests Won’t Forget

By | Lifestyle

Whether your children or grandchildren are starting to plan their weddings, or you are thinking about a vow renewal, there are some new wedding trends you should know about. Many of these trends reflect a more heart-centered, memorable approach designed to help guests cherish the memory and feel a part of the celebration forever.

Weddings are no longer defined solely by scale or visual impact, but by something less tangible and more lasting: experience and interaction. From live painters to intimate destination weekends, the newest trends are all about creating meaningful experiences for couples, their families, and their guests.

It’s All About The Experience

Today’s receptions are increasingly interactive. Couples are swapping traditional entertainment for experiences that invite guests to participate rather than simply observe. Live portrait artists, mobile cocktail bars, and even late-night ice cream trucks keep energy high while giving guests something unexpected to enjoy.

The standard is no longer simply to host a beautiful wedding. It’s to create a feeling guests carry home with them long after the last dance. The most memorable celebrations now include thoughtful touches emphasizing connection, participation, and storytelling across different generations.

Interactive Welcome Wall

One of the most popular trends right now is creating a guest welcome experience that goes beyond traditional signage. Champagne walls let guests grab a drink as they arrive and can easily be personalized with sparkling juices, craft sodas, or even a donut display for a sweeter touch. More than just a photo opportunity, these interactive details encourage interaction among guests as they arrive and mingle, setting a celebratory tone from the moment they arrive, turning the entrance into part of the experience.

Generations of Love

Family-centered traditions are evolving too. Instead of an in-memoriam table, some couples are choosing a more uplifting approach with a generations of love display. Often featuring wedding photos from parents, grandparents, and even great grandparents, it becomes less about mourning and more about honoring and celebrating family legacy.

Live Wedding Painters

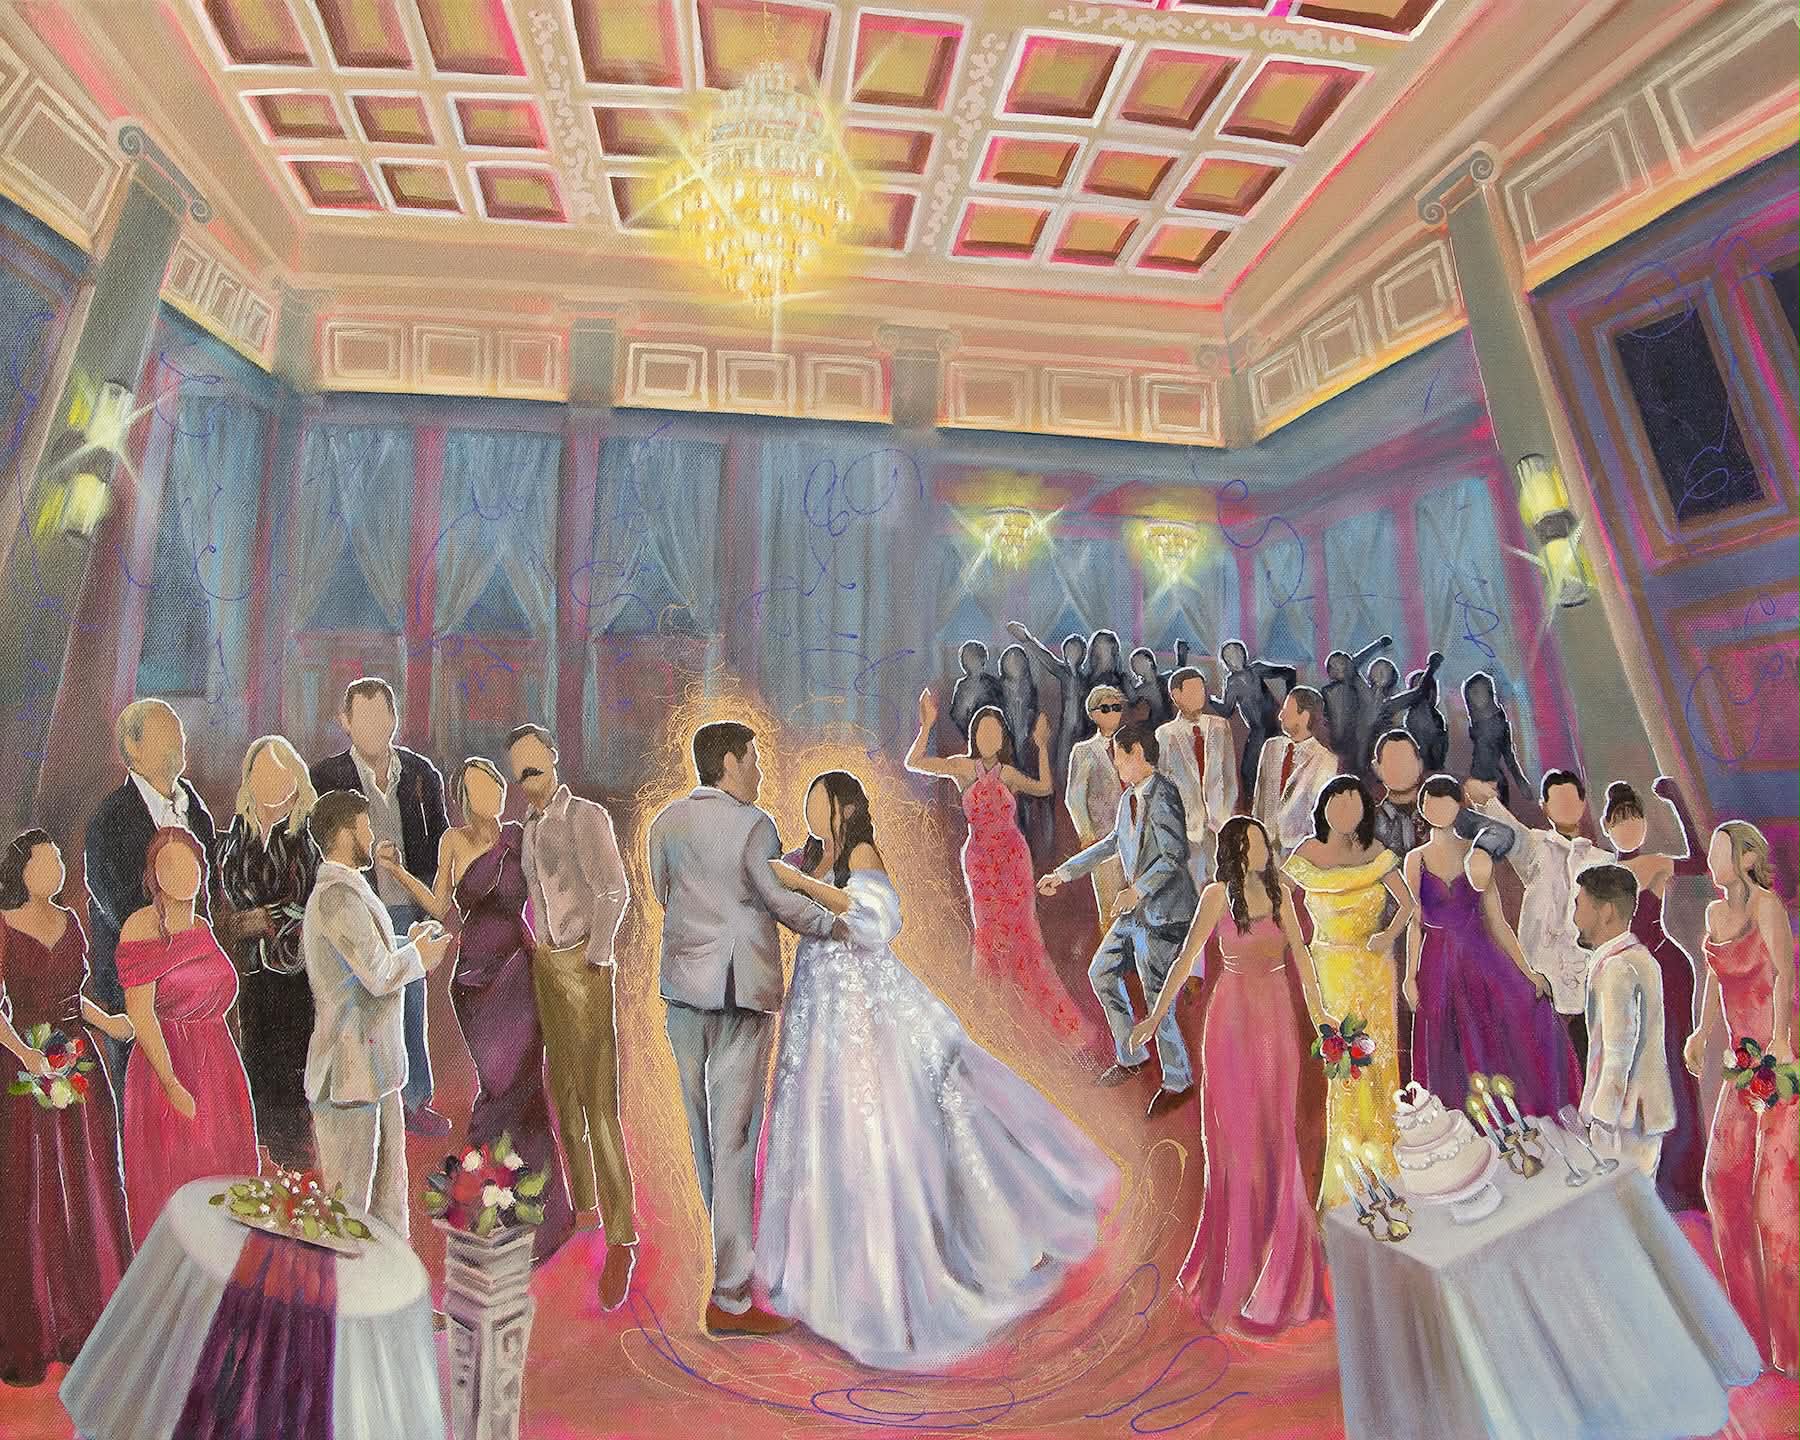
Live wedding painters are becoming a sought-after addition to modern weddings and other live events, offering couples a unique way to preserve not just how the day looked, but how it felt. Styles can range from hyper realistic portraits to impressionistic scenes, allowing couples to choose the artwork that reflects their personality and aesthetic. Whether it’s a single artist capturing the ceremony scene or a duo including a speed painter creating mini guest portraits in real time, it creates a dynamic and interactive moment for your guests as they watch the wedding portrait come to life or receive their own deeply personal, one-of-a-kind painting.
Dedication Bouquet

Many brides are opting to forgo the traditional bouquet toss in favor of personally selecting who the bouquet goes to. This is a great way to show a moment of gratitude to a parent, grandparent, or mentor who played a meaningful role in the journey to the wedding. Some brides reserve a special flower within their bouquet, while others dedicate the entire bouquet. These quieter moments often become an emotional highlights guests remember fondly.

Handwritten Notes

Perhaps one of the most touching trends right now is the return of handwritten notes. Couples are placing individual notes or thank you cards at each guest’s seat, expressing why their presence there matters in a few personal words. Although time consuming, it adds a heartfelt, personal touch and is often a detail guests will hold onto long after the day is over.

Alternative Table Number Ideas

Instead of standard numbered tables, couples are finding new and creative ways to tell their story. Some use childhood photos from different ages as table markers, while others leave notebooks at each table so guests can write advice for the couple to read on a future anniversary that matches the table number. It’s a simple way to turn the wait before dinner into something interactive, giving guests a fun activity and an instant conversation starter.

Sentimental Keepsakes

Even small paper details are becoming keepsakes. Customized cocktail napkins featuring handwritten notes, pet illustrations, inside jokes, or family recipes add personality in a way that feels timeless. These are details guests often slip into a bag and actually hold onto.

Interactive Guest Books

Interactive guest books are also going beyond simple signatures. Photo booths with instant prints, recorded video messages, vintage voicemail stations, and written advice cards all encourage guests to leave behind something more meaningful and personal than just their signature. It becomes less about attendance and more about personal connection.

Intimate Destination Weddings

While big traditional weddings are not going anywhere, intimate destination weekends are becoming increasingly more appealing, especially among affluent families. Instead of devoting a substantial budget around single-day celebrations, couples are choosing to invest in a full weekend experience built around shared meals, excursions, and unstructured time together. For many multigenerational families, particularly those spread across the country, the wedding becomes a rare reunion and a moment shared intimately with those nearest and dearest.

The Anniversary Dance

Many DJs are suggesting an anniversary dance, where married couples are invited onto the dance floor and gradually sit down based on how long they’ve been married until one couple remains, encouraging guests onto the dance floor and creating one of the evening’s most emotional moments. Simple, interactive, and unexpectedly moving, It becomes a shared experience for many guests and often feels both celebratory and quietly inspiring for younger generations.

Ultimately, the weddings that guests remember most are rarely the ones defined by scale or visual aesthetics.  They’re the celebrations that made people feel truly welcomed, included, and emotionally connected. It also reflects how has evolved at high-end weddings. Beyond design and décor, couples are thinking more about flow, interaction, and small intentional moments that shape the guest experience. The details may vary, but the lasting impression comes from thoughtful experiences that make everyone feel part of something meaningful.


If there’s a wedding in your family’s future, and you’re starting to think about how your multigenerational family will celebrate and divvy up expenses, now is a good time to schedule a conversation and map out what that could look like for you financially. Contact us today!


Sources

https://www.brides.com/unique-wedding-ideas-4845957

https://www.theknot.com/content/new-wedding-trends


Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-121

Don’t Take The Bait: How To Spot A Phishing Scam Before It’s Too Late

By | Cybersecurity

Phishing is the most reported type of cyber scam in the United States and worldwide, and these attacks continue to rise and evolve every day. In 2024, the Better Business Bureau established National Scam Survivor Day, observed on the second Thursday in May. Throughout the month, the BBB, FBI, and National Cybersecurity Alliance lead awareness campaigns focused on common scams and prevention strategies. As phishing scams grow more sophisticated, retirees and high-net-worth (HNW) individuals must stay vigilant because even the most careful investors can fall victim to scams that result in significant financial loss and disruption.

Phishing 101: The basics

Phishing gets its name from the idea that attackers are “fishing” for victims by using spoofed or fraudulent messaging as bait. It’s a type of online scam where someone pretends to be a trusted source to trick you into sharing your personal details, login credentials, or payment information. These attacks can come through email, text, phone calls, or anywhere online and can result in identity theft, hacked accounts, and lost funds.

Common types of phishing attacks

  • Email phishing (Mass-market impersonation): The most common form of phishing. Attackers send fraudulent emails that appear to come from government agencies or other legitimate entities, urging recipients to click on links, open attachments, or provide sensitive information. For example, scammers have recently impersonated the IRS during tax season, sending emails claiming an issue with a taxpayer’s return or refund. Corporations and their employees in various industries are also being targeted. Regulators have recently issued warnings about an “agent phishing” scam in which attackers have pretended to be the National Insurance Producer Registry (NIPR), sending fake past-due invoice emails to insurance agents, applicants, and administrators.
  • Spear phishing (Targeting): Attackers specifically target high-value victims and organizations using specific or personalized information to make the attack appear legitimate. This is highly effective because attackers tailor messages to the recipient, such as referencing a conference or recent event the recipient may have just attended or using filenames tied to topics of interest.
  • Vishing (Voice phishing): Scammers use phone calls to impersonate legitimate individuals or organizations, often claiming urgent issues to pressure victims into providing sensitive information. Recent attacks increasingly use AI-generated voices to mimic real people and sound more convincing.
  • Smishing (SMS/text phishing): Similar to email phishing but conducted through text messages. If your phone number has been exposed after a data breach, you may find yourself on the receiving end of more smishing attacks. USPS scam texts are a common example, where fake delivery or purchase notifications urge you to tap a link to confirm or resolve an issue.
  • And other tactics: Fake public Wi-Fi networks, lookalike website domains, pop-up internet ads, and various other methods.

Hook, line, and sinker: Red flags to watch for

Phishing emails and messages often rely on familiar names and urgent language to prompt quick action. Be cautious of emails or messages that appear to come from well-known, trusted organizations like LinkedIn, Amazon, or the IRS.

  • Always look closely for misspellings or added/substituted characters in the sender address. Legitimate companies use official domains, for example Amazon emails will come from an address ending only in “@amazon.com,” not “@amazon-support.com” or other variations.
  • The IRS, SSA, and other official U.S. government agencies will never initiate contact through email, text, or social media.
  • Watch for generic or suspicious subject lines, such as “Mail Notification: You have 5 Encrypted Messages,” “Undelivered Mail Returned to Sender,” or “Action required: Your payment was declined.”

Other common red flags can include:

  • Poor grammar, generic greetings, unexpected prizes and offers, and requests for personal information.
  • Urgent threats such as account suspension or limited-time demands to act.
  • Subtle changes like “rn” instead of “m” in links and URLs.
  • Unusual attachments or file names from unknown senders.
  • Poorly formatted emails, broken links, multiple fonts, or colors and logos that don’t match the company’s official branding.

Additionally, the Department of Social Security Administration (SSA) has identified four key warning signs to help recognize and avoid scams, known as the four Ps:

  1. Pretend: Scammers pretend to be a trusted source
  2. Problem: Scammers will fabricate an issue to intimidate recipients
  3. Pressure: Scammers will pressure recipients to act immediately
  4. Pay: Scammers will request payment in specific ways such as through gift cards, online transfers, or money orders.

How to protect yourself

  • Think before you click: If you receive a suspicious invoice or request from an email claiming to be from USPS, FedEx, Amazon, or another organization, do not open any attachments, click any links, or submit payment. Instead, verify the legitimacy by contacting the organization directly using an official email address, phone number, or secure message center.
  • Use strong, unique passwords: Passwords should be long, complex, and never based on birthdays, pet names, or other personal details. Shoot for 16 characters or more, including a mix of letters, numbers, and special characters.
  • Multi-factor authentication (2FA): More sites and apps now offer two-factor authentication, adding an extra layer of security beyond a username and password. By requiring multiple forms of verification, it makes it much harder for cybercriminals to gain access to your account.
  • Antivirus security software: Install reputable antivirus security software, and keep software and devices updated automatically, to detect and thwart phishing campaigns in real time. Forbes lists Norton, TotalAV, Avast, Aura, and McAfee among top-rated security software options for 2026.

You’ve worked hard to build and preserve your financial security. Don’t let it be compromised by a moment of uncertainty. Always verify before responding. If something doesn’t look right, trust your instincts!

As licensed financial professionals, we are committed to helping you protect and preserve your wealth in every way we can. If you ever receive a suspicious message, our team is here as a resource to provide a second opinion before you take action. Bulwark Capital Management can help you stay on track, adjust as needed, and support you in making steady progress toward your financial future.


Sources:

  1. https://www.fbi.gov/how-we-can-help-you/scams-and-safety
  2. https://victimsofcrime.org/event/scam-survivor-day/
  3. https://consumer.ftc.gov/articles/how-recognize-avoid-phishing-scams
  4. https://www.statista.com/topics/8385/phishing/#topicOverview
  5. https://www.consumerfraudreporting.org/current_top_10_scam_list.php
  6. https://www.newsminimalist.com/articles/interpol-online-scams-phishing-are-top-global-cybercrimes-b001f2d2
  7. https://lifelock.norton.com/learn/fraud/types-of-phishing
  8. https://www.csoonline.com/article/563353/8-types-of-phishing-attacks-and-how-to-identify-them.html
  9. https://www.kaia.com/2025/06/02/phishing-scam-targeting-agents-be-aware/
  10. https://department.va.gov/privacy/fact-sheet/the-four-ps-of-spotting-fraud/
  11. https://www.amazon.com/gp/help/customer/display.html?nodeId=Teu845SZK0ApsIgmGC


DISCLOSURE

Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-108

Travel Tips You Didn’t Know You Needed

By | Lifestyle

Everyone knows the basics of travel. You should pack your passport, get to the airport early, and double-check your reservations. But it’s often the small, overlooked tips that make the biggest difference in how smooth your trip feels.

Here are some underrated travel tips you can start using on your upcoming summer trips that can completely change your experience.

  1. Save Your Must-Visit Spots in Google Maps Before You Go

Instead of scrambling to search for restaurants or attractions right after you arrive in a new city, save everything in advance on Google Maps while planning your trip. You can create lists like “Hawaii 2026,” “Summer Vacation,” or “Greece” to help you remember what each location is for. You can even take it a step further and create custom lists for each day of your trip for those of you who are Type A travelers.
  1. Download Offline Maps and Avoid Roaming Fees

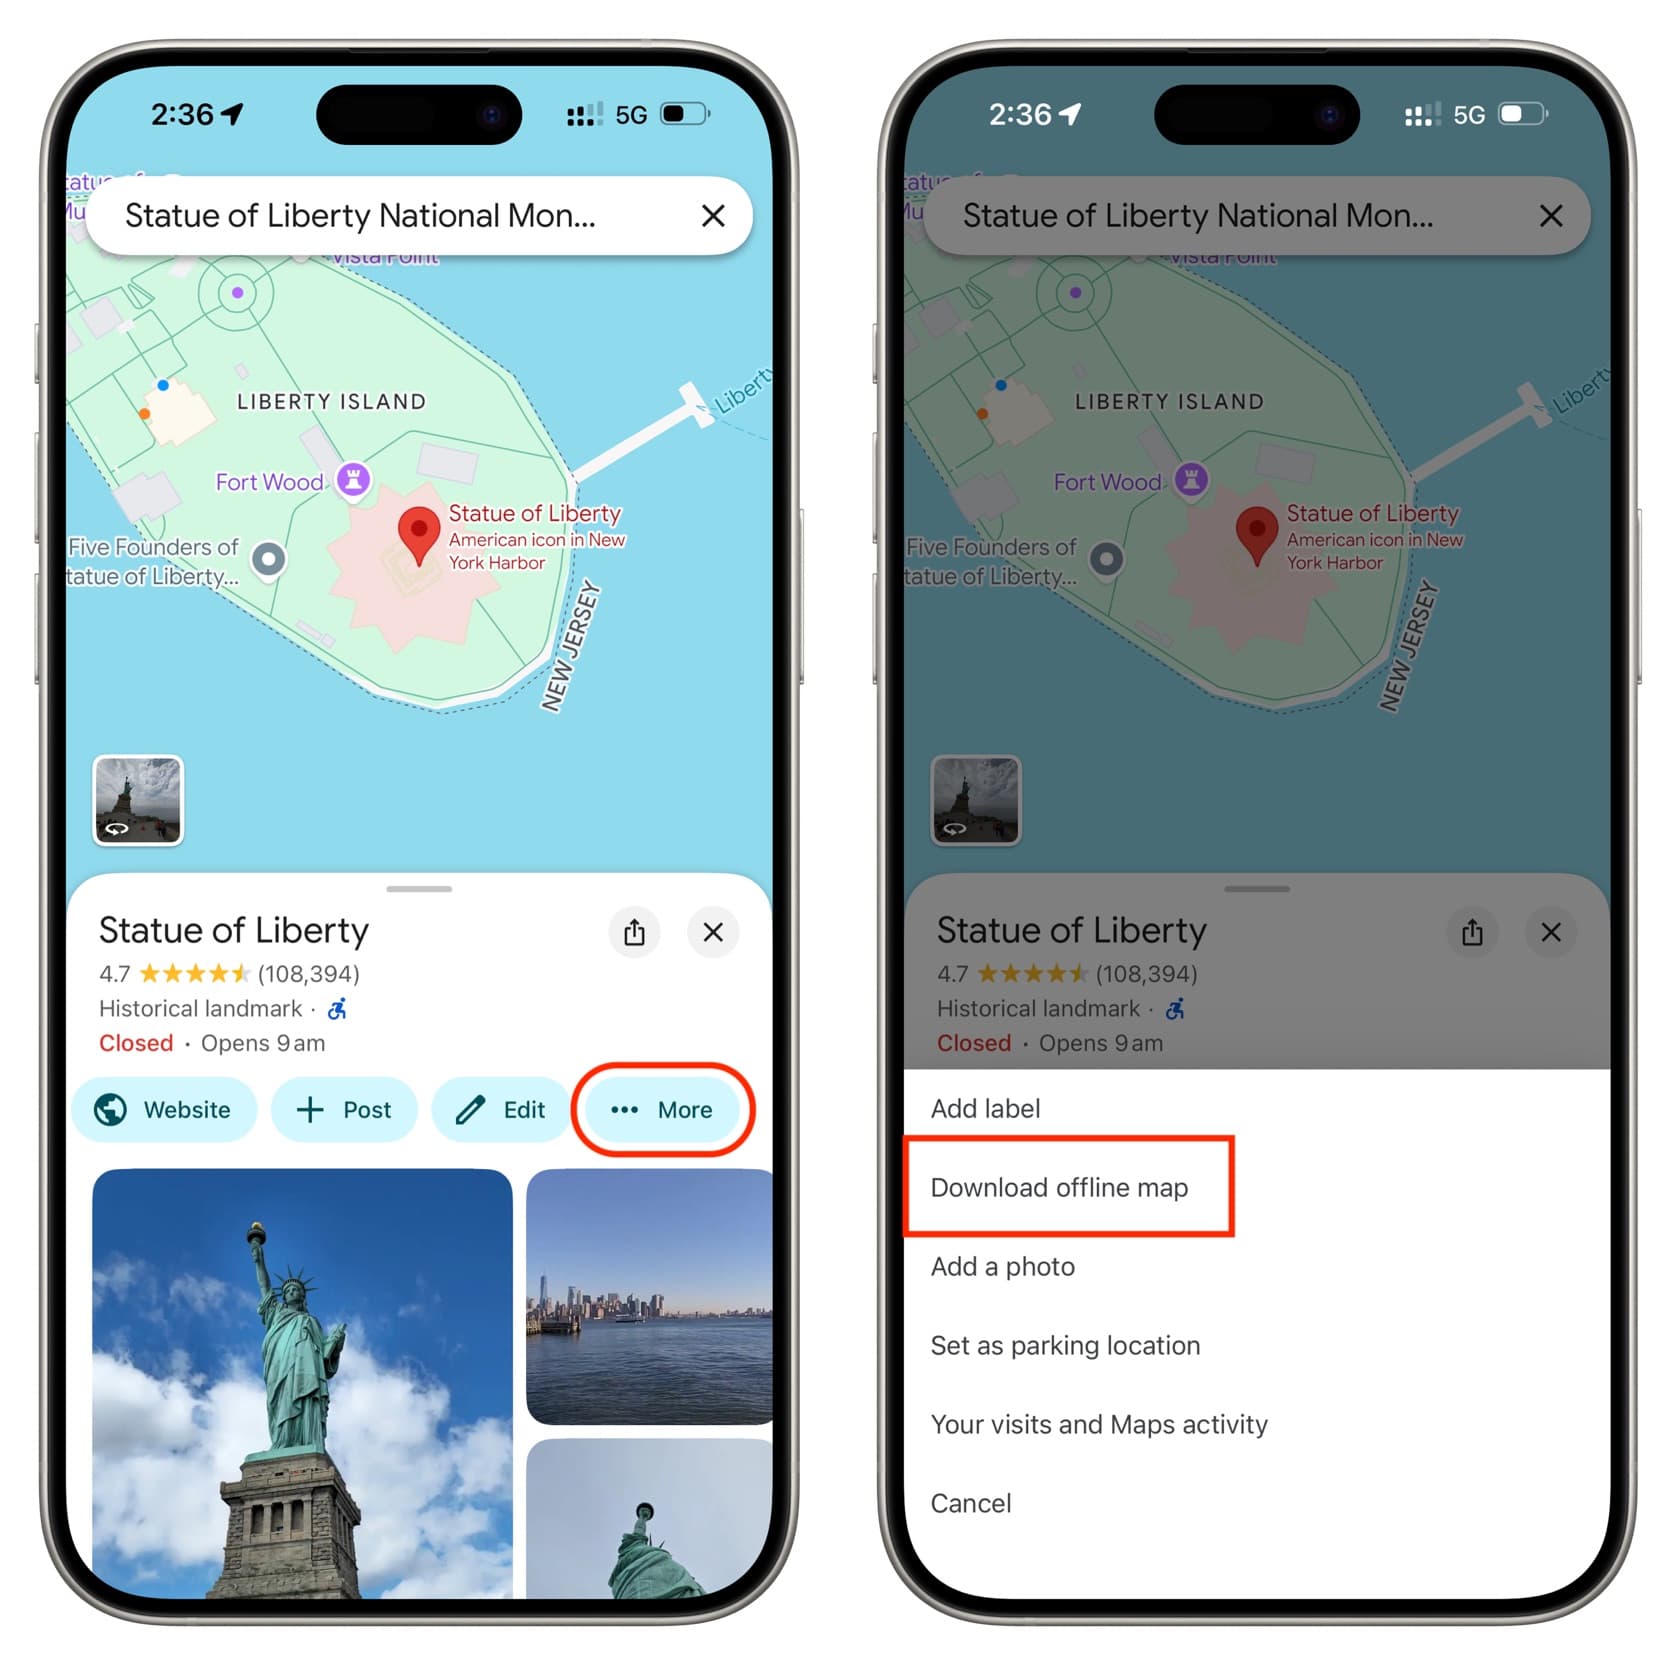
International data charges add up fast. For example, plans like AT&T’s International Day Pass or Verizon’s TravelPass can cost around $12 per day, which becomes expensive on longer trips. Even in popular cities or crowded tourist areas like New York City or Chicago, cellular service can be unreliable due to network congestion and tall buildings that interfere with signal strength.
For those looking to avoid charges or wanting reliable navigation no matter where you are, you can download offline maps in Google Maps before you leave and access them when you arrive.

  1. Consider an eSIM Instead of Data Roaming

If you still want access to data abroad but don’t like the pricing from your carrier, you can potentially use an eSIM instead of paying daily roaming fees. Most newer smartphones support eSIMs, but you’ll want to confirm that your device is compatible and that your carrier allows you to use one. Some carriers “lock” phones, meaning they restrict you to their network and may prevent the use of third-party or international eSIMs.

Companies like Airalo, Holafly, and Simify offer digital SIM cards that you can install directly on your phone.

  1. Match Your Trip Length to Your Flight Time

This one is more of a personal rule, but it makes a big difference. If you’re flying 6–14 hours to get somewhere like Hawaii, London, or Sydney, consider staying for a similar number of days. Long-haul travel takes a toll on your body, and shorter trips don’t always give you enough time to adjust and truly enjoy the destination.

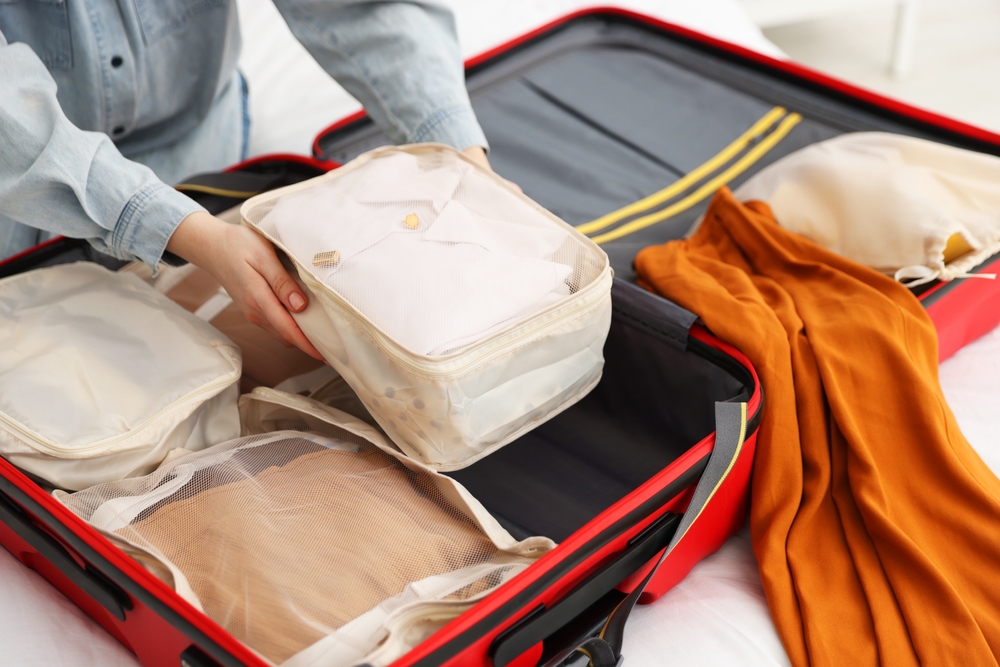
  1. Use Packing Cubes to Stay Organized

Packing cubes are one of the simplest “upgrades” you can make when planning your trip. They help save space, keep outfits organized, and prevent overpacking. Instead of digging through your entire suitcase, everything has its place, and you can organize your cubes however you prefer—by outfit, clothing type, or weather.
  1. Use AirTags to Track Your Belongings

If you are an Apple user, traveling with AirTags can give you serious peace of mind. Most people use them to track their luggage in case it gets lost. Once you arrive at your destination and your luggage is with you, you can keep one in your bag to help prevent theft or even place one in a child’s shoe or pocket in crowded areas.

  1. Invest in “Pickpocket Proof” Gear

Pickpocketing is common in major cities in Europe, and local authorities may not always be able to help, so it’s important to take precautions yourself!

Consider using anti-theft crossbody bags with secure zippers or money belts worn under your clothing. If you don’t want to buy new gear, you can secure your current bag by attaching a carabiner (even one from a water bottle) to your zipper.

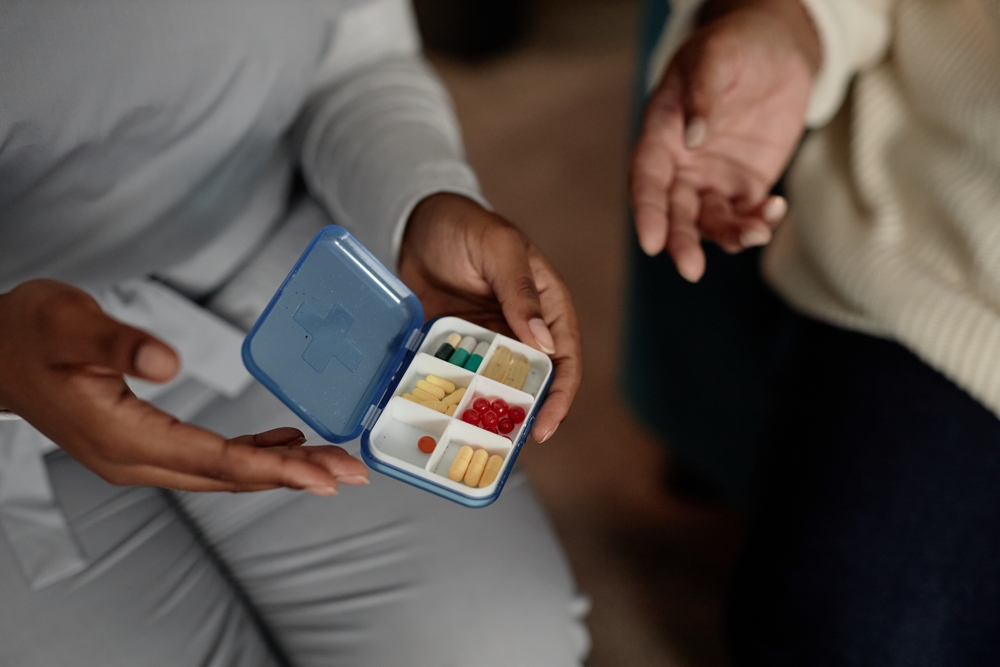
  1. Bring a “Pocket Pharmacy”

Pharmacies abroad can be confusing, with different brands, languages, and sometimes limited hours. It’s best to save yourself from the headache (and the pain reliever you will need to help fix it!) by bringing small quantities of medications with you.

A compact pill case can hold essentials like pain relievers, allergy medication, antacids, sleep aids like melatonin, vitamin C or zinc if you start to feel sick, and motion sickness pills. Being prepared helps save time when you’re not feeling your best.

  1. Use Cards Over Cash (But Keep Some Coins)

While it’s common to carry cash, almost all places now accept cards, and using them can actually reduce your risk. If your card is lost or stolen, you can quickly lock it through your online banking app. Cash, on the other hand, is gone for good.

That said, we still recommend keeping some small coins, as in many parts of Europe public restrooms require around €1 and coins make that much easier.


These aren’t flashy “travel hacks,” but they’re the ones that seasoned travelers keep coming back to and rely on most. With a little preparation and easy-to-use tools, your travel experience can be far less stressful, allowing you to focus on enjoying your vacation instead of managing it.

Bon voyage!


Sources:

  1. https://www.idownloadblog.com/2016/04/04/download-google-maps-offline-use/
  2. https://www.nickgracilla.com/posts/export-google-maps-saved-places/
  3. https://www.businessinsider.com/reference/how-to-save-a-location-on-google-maps


DISCLOSURE

Investment Advisory Services offered through Trek Financial LLC, an investment adviser registered with the Securities Exchange Commission. Information presented is for educational purposes only. It should not be considered specific investment advice, does not take into consideration your specific situation, and does not intend to make an offer or solicitation for the sale or purchase of any securities or investment strategies. Investments involve risk and are not guaranteed, and past performance is no guarantee of future results. For specific tax advice on any strategy, consult with a qualified tax professional before implementing any strategy discussed herein. The content is developed from sources believed to be providing accurate information; no warranty, expressed or implied, is made regarding accuracy, adequacy, completeness, legality, reliability, or usefulness of any information. Consult your financial professional before making any investment decision. Trek 26-108